Using a Self-Directed IRA to Buy Investment Real Estate
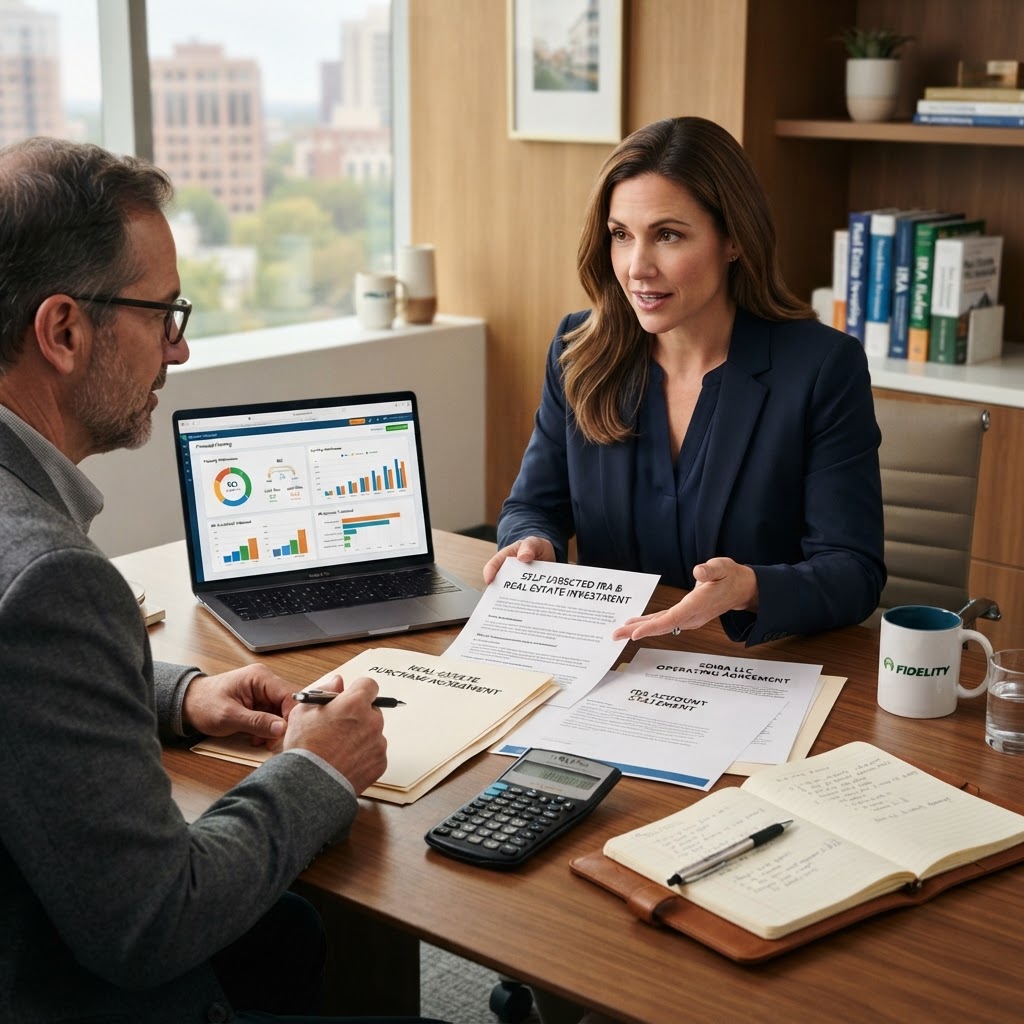
Using a Self-Directed IRA to Buy Investment Real Estate
A self-directed IRA allows you to hold real estate and other alternative assets in your retirement portfolio. Learn how to navigate the rules to achieve true diversification without triggering tax penalties.
Using a Self-Directed IRA to Buy Investment Real Estate
Most people picture stocks and mutual funds when they think of an IRA. A self-directed IRA opens the door to something much broader. With the right custodian, your retirement account can hold investment real estate, private equity, precious metals, cryptocurrency, promissory notes, and more. For investors who want true diversification beyond the public markets, a self-directed IRA can be a powerful tool.
This guide explains what a self-directed IRA is, how it works, how to set one up, and the rules you must follow when using it to buy real estate. For a deeper look at how Randall Parker, MBA helps clients structure self-directed retirement accounts, visit our Self-Directed IRA page at https://randallparkermba.com/RetirementSDIRA.
"Expert tax guidance can mean the difference between compliance and costly penalties, especially for Americans living abroad."
Randall Parker, MBA
What Is a Self-Directed IRA?
A self-directed IRA is simply an Individual Retirement Account held at a custodian that allows alternative investments. The self-directed label is descriptive, not a separate legal category. It means you, the account owner, choose the investments instead of picking from a pre-set menu of mutual funds.
The key difference is the custodian. Traditional brokerages limit you to publicly traded securities. A truly self-directed custodian, such as a state-chartered trust company or an IRS-approved non-bank custodian, permits any investment allowed by the Internal Revenue Code. That includes real estate, which has been a permitted IRA investment since IRAs were created in 1974.
You can open a self-directed version of nearly every retirement account: Traditional IRA, Roth IRA, SEP-IRA, SIMPLE IRA, Solo 401(k), and even an HSA or Coverdell ESA. The contribution limits and tax treatment follow the same rules as the standard version of each account.

How a Self-Directed IRA Works
The account is held in the name of the IRA, not in your personal name. Your custodian executes transactions on the IRA's behalf. When you find an investment, you direct the custodian to make the purchase, and the asset is titled to the IRA.
All income and expenses flow through the account. Rental income goes back into the IRA. Property taxes, insurance, repairs, and management fees are paid from IRA funds. You cannot pay these costs out of pocket, and you cannot deposit rental checks into your personal bank account. Everything must stay inside the IRA to preserve the tax advantage.
Many investors add a layer of control with a Checkbook IRA LLC. In this structure, the IRA invests in an LLC that you manage. The LLC opens a bank account, and you can write checks and execute transactions without waiting on the custodian for each one. This works well for real estate, where speed and ongoing expense management matter. The LLC must be set up correctly, with an operating agreement that meets IRS requirements, and you serve as manager, not owner. The IRA owns the LLC.
How to Establish a Self-Directed IRA
Setting up an account takes a few clear steps.
 Choose a qualified custodian. Look for a state-chartered trust company or an IRS-approved non-bank custodian. Verify their status before you commit. The Retirement Industry Trust Association (RITA) is a good starting point for finding reputable providers.
- Open the account. Most custodians let you start the process online. You will choose the account type, such as Traditional, Roth, SEP, or Solo 401(k).
- Fund the account. You can fund it with a direct contribution, a transfer from an existing IRA, or a rollover from a qualified plan like an old 401(k). Transfers and direct rollovers avoid taxes and penalties.
- Direct your investments. Once funds are in the account, you tell the custodian what to buy. If you use a Checkbook IRA LLC, you form the LLC, open its bank account, and then invest directly from that account.
- Stay compliant. Keep records, file required reports, and avoid the prohibited transactions described below.

The Seven Essential Rules for Real Estate in a Self-Directed IRA
The Entrust Group outlines seven core rules that govern real estate held in a self-directed IRA. These rules protect the tax-advantaged status of your account. Breaking them can trigger a prohibited transaction, which can disqualify your entire IRA and result in taxes, penalties, and interest.
1. Avoid Prohibited Transactions
You cannot use your IRA for personal benefit beyond the growth of the account. A prohibited transaction is any deal in which you or a disqualified person gains a personal advantage from the IRA's investment. The consequences are severe. The IRA loses its tax-exempt status from the first day of the year the violation occurs, the entire balance is treated as a taxable distribution, and a 10 percent penalty may apply if you are under age 59 and a half.
2. Know Who Counts as a Disqualified Person
Disqualified persons include you, your spouse, your children, grandchildren, parents, and certain other family members and entities. Your IRA cannot do business with these people. You cannot sell property you personally own to your IRA, and you cannot buy a property from a family member into your IRA. Fiduciaries, such as your financial advisor or the custodian, are also disqualified.
3. No Personal Use of the Property
Neither you nor any disqualified person can live in, vacation in, or use the property owned by your IRA. This rule applies even if you pay fair rent. The IRS views any personal use as a prohibited benefit. You also cannot let a family member live in the property rent-free or below market.
4. Title the Property Correctly
Real estate bought by a self-directed IRA must be titled in the name of the IRA, not your name. A typical title reads something like Entrust Trust Company FBO [Your Name] IRA. If you use a Checkbook IRA LLC, the LLC holds title. Improper titling can disqualify the investment and trigger taxes.
5. All Income and Expenses Flow Through the IRA
Rental income, sale proceeds, and any other earnings go back into the IRA. Property taxes, insurance, maintenance, and management fees are paid from IRA funds. You cannot pay expenses personally, even as a convenience, and you cannot keep income personally. Mixing personal and IRA funds is one of the fastest ways to create a prohibited transaction.
6. Watch for UBTI and UDFI When You Use Debt
If you buy real estate with all cash from your IRA, there is no unrelated business income tax issue. But if you finance the purchase with a loan, the debt-financed portion of the income may be subject to Unrelated Debt-Financed Income (UDFI) tax. The IRA itself pays this tax, and the custodian files Form 990-T on the account's behalf.
For example, if 60 percent of a property is financed with a non-recourse loan, then roughly 60 percent of the rental income or gain is subject to UDFI tax. Only non-recourse loans are permitted inside an IRA, meaning the lender cannot come after you personally. This restriction makes IRA financing harder to find and often more expensive.
7. You Cannot Personally Guarantee a Loan for the IRA
Because the IRA is a separate entity, you cannot sign a personal guarantee on a loan to the IRA. Any loan must be non-recourse, secured only by the property itself. This protects your other assets but limits leverage and can reduce overall returns. Plan your financing strategy accordingly.
Other Investment Options in a Self-Directed IRA
Real estate is the most popular alternative investment, but it is far from the only one. A self-directed IRA can also hold:
- Private equity and private placements
- Promissory notes and private lending
- Precious metals, such as gold and silver that meet IRS purity standards
- Cryptocurrency
- Tax liens and certificates
- LLCs and other entity interests
- Water and mineral rights
The common thread is that the IRA, not you, owns the asset. Returns grow tax-deferred in a Traditional account or tax-free in a Roth, as long as you follow the rules.
Is a Self-Directed IRA Right for You?
A self-directed IRA is not for everyone. It requires more hands-on management, a clear understanding of the rules, and the discipline to keep personal and retirement finances separate. For investors who already understand real estate or alternative assets, the upside can be meaningful. You gain tax-advantaged growth on an asset class you know, and you diversify away from the volatility of the stock market.
The risks are real. A single prohibited transaction can wipe out years of tax savings. That is why it pays to work with a knowledgeable custodian, a qualified attorney for any LLC setup, and a tax professional who understands the nuances of UBIT and UDFI.
If you are considering a self-directed IRA for real estate or any other alternative asset, the right guidance makes all the difference. Randall Parker, MBA helps clients evaluate whether a self-directed structure fits their retirement goals and ensures the setup stays fully compliant. Learn more on our Self-Directed IRA services page at https://randallparkermba.com/RetirementSDIRA, or reach out for a free consultation.
More Articles

Have Questions About This Topic?
Schedule a free consultation with Randall Parker, MBA, 40+ years of tax and financial expertise at your service.
Schedule Free Consultation →