Philippines PERA Accounts and Foreign Retirement Programs for US Expats: A Comprehensive Guide
Philippines PERA Accounts and Foreign Retirement Programs for US Expats: A Comprehensive Guide
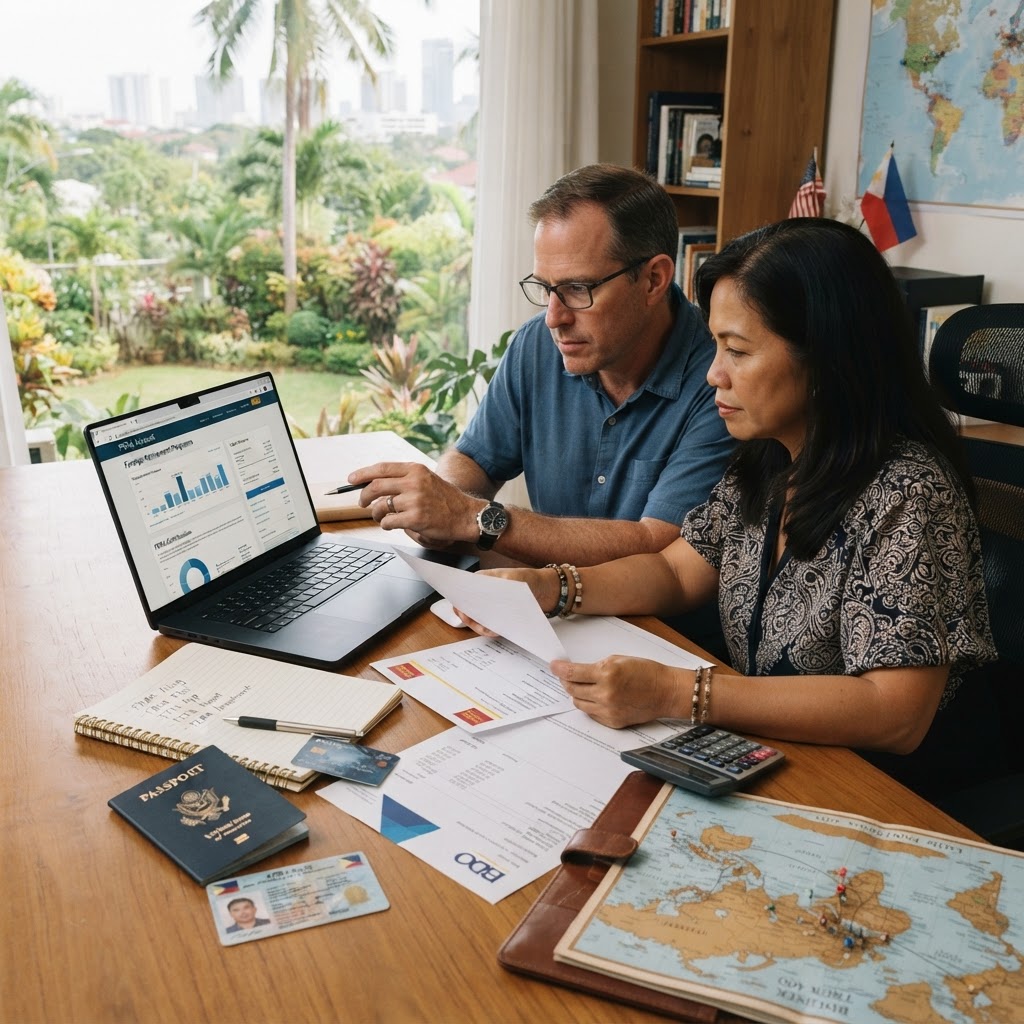
Navigating retirement savings as a US expat is complex. This guide explores the Philippine PERA account and other international retirement vehicles, focusing on the critical US tax implications every American abroad must understand.
Introduction: The Complexity of Expat Retirement Planning
For many US citizens living abroad, the allure of local investment vehicles is strong. Whether it is the Philippines Personal Equity and Retirement Account (PERA) or similar programs worldwide, these accounts often promise tax advantages in your host country. However, as a US taxpayer, you remain subject to global taxation. The interplay between local retirement laws and US tax mandates, specifically involving Passive Foreign Investment Company (PFIC) rules, Foreign Trust reporting (Form 3520 and 3520-A), and FBAR/FATCA obligations, turns a simple savings decision into a complex compliance challenge. Understanding these accounts is essential for any expat looking to secure their future without falling into traps set by the IRS.
"Expert tax guidance can mean the difference between compliance and costly penalties, especially for Americans living abroad."
Randall Parker, MBA
The Philippines PERA: A Detailed Breakdown
The Personal Equity and Retirement Account, or PERA, was established under the PERA Act of 2008 to encourage voluntary savings among Filipinos.
Eligibility and Limits
PERA is open to any individual with the capacity to contract and a Tax Identification Number (TIN). This includes resident foreign nationals, such as US expats living in the Philippines. The current annual contribution limit is 100,000 PHP (roughly 1,800 USD) for residents and 200,000 PHP (roughly 3,600 USD) for overseas Filipino workers.
Tax Benefits and Withdrawals
Contributors benefit from a 5 percent tax credit on their annual contribution against their Philippine income tax. Investment earnings are exempt from all Philippine taxes. Qualified withdrawals made at age 55 or older, provided at least five years of contributions have been made, are entirely tax-exempt in the Philippines. Early withdrawals are subject to a penalty of 20 percent on the tax benefits previously enjoyed, plus the potential loss of tax-exempt status on earnings.
US Tax Implications: The Hidden Dangers
While the Philippines treats PERA favorably, the IRS does not recognize it as a qualified US retirement plan.
Reporting and PFICs
Most PERA investments are held in local mutual funds or collective investment schemes. Because these are not US-domiciled, they are almost universally classified as PFICs. This creates a nightmare of punitive tax rates and complex disclosure requirements. Furthermore, if the IRS determines that a PERA constitutes a foreign trust, you may be required to file Form 3520 and 3520-A annually. Failure to do so can result in substantial penalties. You must also include these accounts on your FBAR (FinCEN Form 114) and potentially Form 8938 (FATCA) if you meet the reporting thresholds.
Comparative Global Retirement Programs
Mexico: AFORE
Mexico operates the AFORE system for retirement savings. While accessible to foreigners, these funds are generally viewed as taxable foreign accounts by the IRS, with no treaty-based deferral, often triggering PFIC exposure.
Canada: RRSP and TFSA
Canada represents a unique case. Under the US-Canada Income Tax Treaty, RRSPs are generally recognized as tax-deferred for US tax purposes. TFSAs, however, are not recognized by the treaty and are often treated as taxable foreign trusts or PFICs, creating significant reporting burdens.
United Kingdom: SIPP and ISA
SIPPs can often be structured to align with US tax treaties, but ISAs are generally fully taxable in the US and ineligible for the treaty benefits that apply to pensions.
Australia: Superannuation
Australian Superannuation funds are typically treated as foreign trusts. While the US-Australia tax treaty provides some relief, reporting on Form 3520 is frequently required.
Germany: Riester and Rurup
These programs offer German tax relief but are generally not recognized by the US IRS as qualified plans, leading to immediate taxation of growth for US residents.
Singapore: SRS
The Supplementary Retirement Scheme (SRS) is open to foreigners. It offers excellent local tax deferral, but since there is no specific US tax treaty provision covering it, the IRS views it as a standard foreign investment account.
Japan: iDeCo and NISA
Similar to other nations, iDeCo and NISA lack explicit treaty-based protection for US citizens. Gains are often taxed annually in the US, regardless of the local tax-free status.
Practical Guidance for Expats
Before you open a foreign retirement account, consider the following:
 Tax Neutrality: Is the local tax savings worth the cost of professional US tax compliance?
- PFIC Exposure: Does the account force you to hold assets that the IRS will penalize?
- Treaty Relief: Always confirm if a specific US-host country tax treaty provides exemptions for your specific account type.
- Administrative Burden: Can you afford the professional accounting fees to file the required FBAR, FATCA, and Form 3520 disclosures?
Conclusion and Call to Action
Retirement planning abroad is a balancing act between local incentives and US global tax requirements. Missteps in reporting or investment selection can lead to audit risks and severe financial penalties. If you are an American expat living in the Philippines or anywhere else, do not navigate these regulations alone. Contact Randall Parker, MBA today for a personalized consultation to ensure your international retirement strategy is compliant, efficient, and secure.
More Articles

Have Questions About This Topic?
Schedule a free consultation with Randall Parker, MBA, 40+ years of tax and financial expertise at your service.
Schedule Free Consultation →